The possibility that Panama has insurance to support savers in the banking center is one of the discussions that has opened the financial, political and judicial scandal that is shaking Paraguay.
The regulator’s intervention in the private bank Ueno Bank, as well as the dismissal and arrest of the president of that South American country, Santiago Peña, due to the conflict of interest, have extended the debate on the strength of the banking system to the isthmus. the guarantees for its depositors.
The Superintendency of Banks of Panama (SBP) confirmed exclusively to Panama Starwhich next year will carry outa feasibility study for the creation of a guarantee or deposit fund” in the country.
The matter had already been under evaluation for years by local authorities, confirmed the supervisory institution, led by the superintendent Milton Ayón Wong. However, with the collapse of Ueno Bankthe topic has regained relevance.
Its eventual implementation “requires carefully studying aspects such as the scope of coverage, the amounts protected, the administration model, the financing structure and its articulation with the bank resolution mechanisms.”
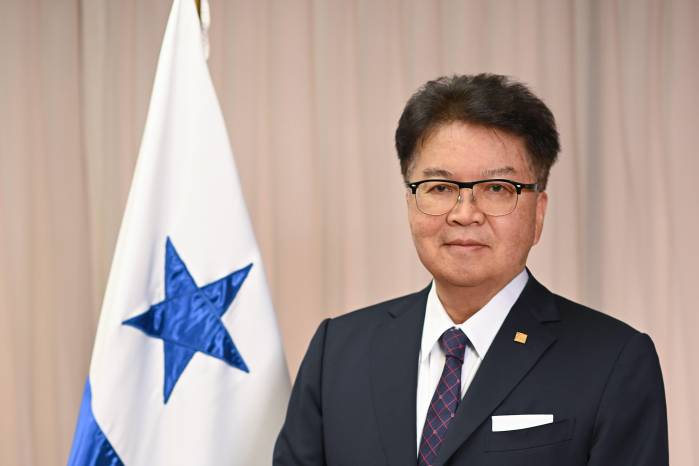
Milton Ayón Wong, superintendent
Precisely, the guarantee fund allowed in Paraguay return at least a part of the resources to 100% of the savers entitled to the deposit guarantee, while the amounts that exceeded the established coverage limit remained pending.
This guarantee fund covers up to 228 million guaraniesequivalent to almost $37,000, depending on the exchange rate.
“Our interest is to continue evaluating the best international practices and alternatives that allow us to strengthen the protection of depositors, without compromising the solidity or competitiveness of our banking center,” answered the SBP to this newspaper.
The entity added that “the protection of public savings is an important element to strengthen the confidence and stability of the banking system. Therefore, it is an issue that deserves a technical and responsible evaluation.”
Who would pay for this insurance?
If implemented, the Superintendency reported that one of the recommended alternatives to finance it would be a model in which banks make regular contributions to a common fund.
In this way, the resources would not come directly from savers nor would they represent a burden on the state budget.
Although it is recommended that banks make contributions to the guarantee or deposit fund, its implementation could have indirect effects for account holders.
“We consider that indirectly this would have an impact on the interest rate that these banks would pay on the deposits that would become covered or protected by said fund,” added the SBP by email, in response to questions from The Dean.
The fundamental thing is that any mechanism in this sense responds to the particularities of Panama as a dollarized economy and preserves the incentives for responsible banking management.
Panama puts its walls to soak
When comparing the regulations of Panama and Paraguay, the Panamanian “significantly surpasses” the Paraguayan in the levels of prudential requirements, risk management, corporate governance and capital conservation buffers, he estimated. Amauri Castillo, former bank superintendent.
However, “we must return to that discussion and explore a scheme to create a private guarantee fund to insure savers’ deposits,” Castillo suggested.
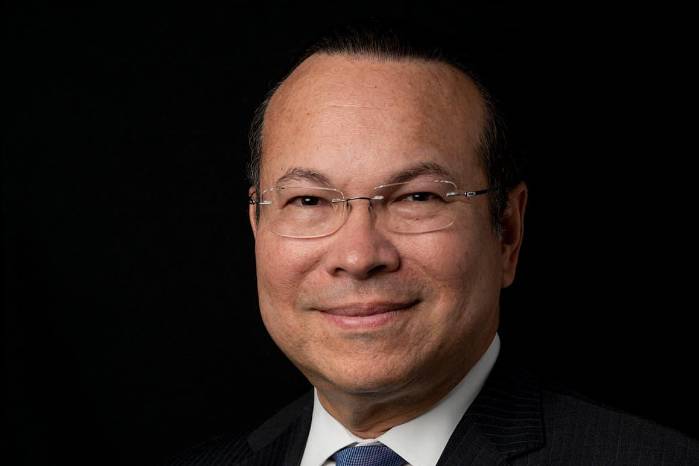
Amauri Castillo, former superintendent 2020 – 2024
The question, he said, is who would finance it. As an alternative, he suggested adopting a model like that of Paraguay, in which banks make proportional contributions to their deposits or assets to create the fund, as also happens in Brazil and other countries.
Currently, what exists is a priority order in the Banking Law that establishes that, in the event of forced liquidation of an entity, the first deposits that must be attended to are those of up to $10,000. This constitutes a kind of “sure” of deposits implicit, described.
In the case of Ueno Bankintervened on November 2, the entity managed $2,061 million in private deposits and $850 million from public institutions and funds destined for retirement and health benefits.
Bank Resolution Law
The main reflection for Panama from this case is the importance of having adequate depositor protection and bank resolution mechanisms that allow timely action in difficult situations in a financial institution, said the SBP.
This is because the stability of the banking system does not depend only on the individual solidity of the banks, but also on the institutional capacity to prevent and respond in an orderly manner to possible risk situations.
For this reason, the SBP analyzes the Paraguayan system and how mechanisms can be designed that protect small depositors, strengthen confidence and contribute to preserving banking stability.
This year, the supervisory entity began a project to define the bank resolution mechanisms, with the advice of International Monetary Fund.
“We are working on a draft of a Preliminary Project of Bank Resolution Law”, which will be presented to Ministry of Economy and Finance next year to have “more flexible and agile mechanisms” that protect depositors and the banking system in general.
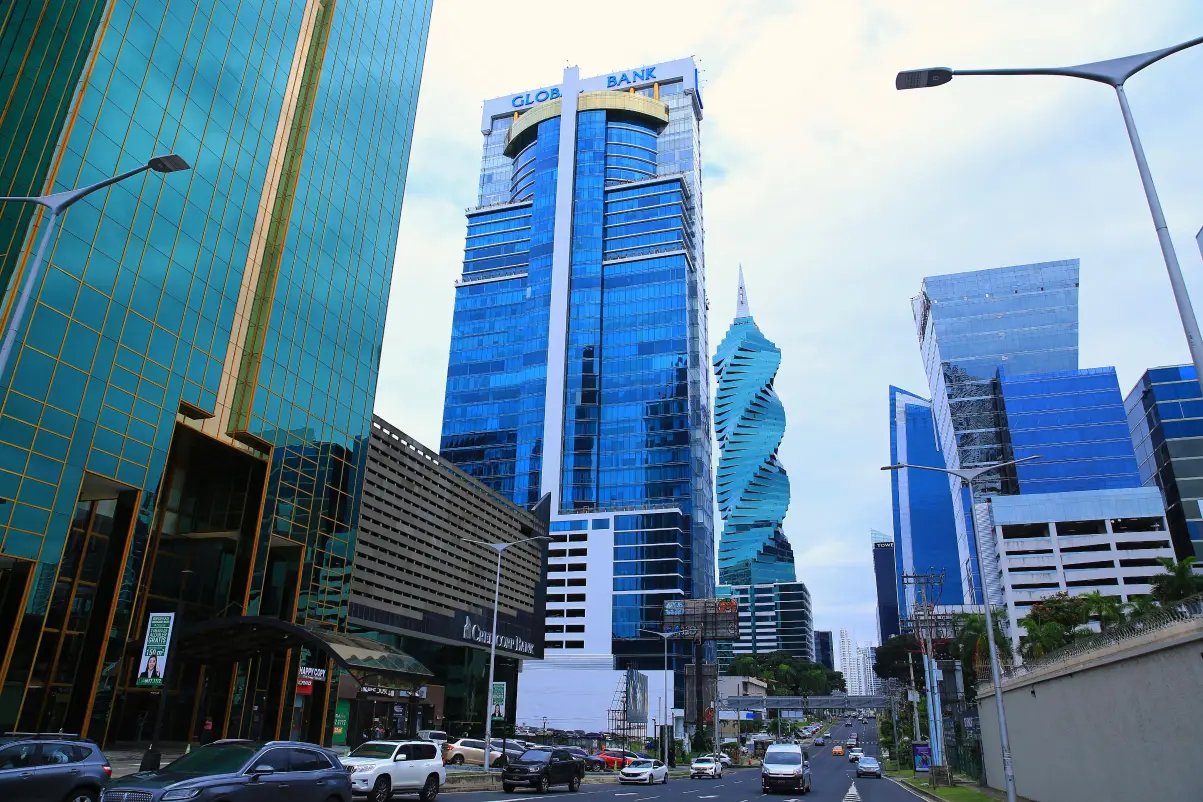
The deposits in the International Banking Center Panamanians constitute the main source of financing and reached the $121,617 millionwhich represents year-on-year growth of the 6.8%according to the most recent report from the SBP as of September of this year.
In the last decade, a dozen banks have been subjected to forced liquidation. Among them are FPB Bankafter investigations of the cases Odebrecht and Lava Jato; Private Banking of Andorra (Panama), accused of money laundering; Atlas Bank; Allbank Corp.; Balboa Bank and Trust; and ES Bank.
Meanwhile, the first bankruptcy due to insolvency occurred in 1996 with Banaic (Agro Industrial and Commercial Bank of Panama).
In 2001the SBP he intervened Disa Bankwhose forced liquidation left more than 600 depositors without your money. The process took about eight years.
Solomon Malcaone of the affected account holders, demanded justice for years and reported that the liquidator informed them that there was no money to pay them.
For its part, the SBP highlighted that the banking system is characterized by prudential supervision, capital and liquidity requirements, and a regulatory framework aimed at preserving stability and confidence. from the public.
However, “as part of the evolution of the financial system, it is also important to continue evaluating tools that strengthen our financial safety net.”