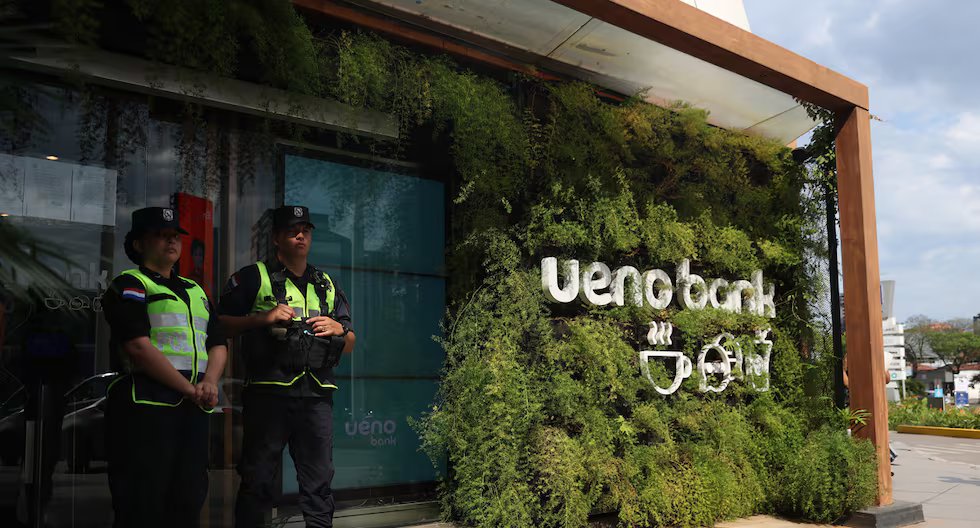

Moody’s pointed out that the crisis of Ueno Bank may have consequences that go beyond the ownership of the entity. In a report, the rating agency warned about the risks for depositors, competition between entities and the regulatory framework of the Paraguayan financial system, following the decision of the Central Bank of Paraguay (BCP) to put Ueno in a resolution process.
Moody’s considered that the case will test the authorities’ ability to manage the resolution of a bank of that size. As of September 2026, Ueno Bank concentrated 9% of the deposits and 8% of the system’s loans.
One of the main risks identified by the rating agency is in the deposits that exceed insurance coverage. Although the BCP indicated that 97% of depositors would be fully covered, only 30% of the value of Ueno’s deposits was within the guarantee limit.
The coverage reaches 75 minimum monthly salaries, equivalent to 228.3 million guaraníes (about US$38,000) per depositor and per institution, once the debts have been compensated. Excluding the Social Security Institute (IPS) and other public entities, uninsured balances represent around 40% of Ueno’s deposits.
In that sense, Moody’s warned that these creditors will have to claim against the bank’s residual assets and that their recovery is uncertain. Additionally, he noted that some depositors, including companies, may face delays or losses.
The crisis could also disrupt competition for deposits. Moody’s anticipates that, following the departure of Ueno Bank the sector’s financing costs moderate, after three years of intense competition to raise funds, driven in part by the growth of the entity.
In this scenario, Itaú Paraguay, Continental, Sudameris and GNB appear among the main potential beneficiaries. According to the report, the four banks hold around 60% of the system’s deposits and would be the most favored by an eventual reallocation of funds.
Regarding the risk of contagion, Moody’s considered that it could remain limited if the process develops quickly and orderly. He estimates that the impact on the real economy would be “modest and temporary.” The rating agency also stated that the case could lead the BCP to tighten capital requirements and accelerate the adaptation of Paraguayan regulation and Basel III standards.
The report also highlighted that, despite the deterioration in the quality of consumer loans, problem loans represented 2.5% of gross loans, compared to 2.1% in December 2025 and were 113% covered by reserves.
As recalled, BCP made the decision, on November 3, to put the bank in a resolution process, after a supervisory review and adjustments to the financial statements of Ueno Bank They will leave their solvency index below 50% of the regulatory minimum. The auditors appointed by the agency must now evaluate the financial situation, protect assets and determine the applicable mechanism.