Banking institutions go out to local communities in search of new clients:

father-in-law
Expressiveness
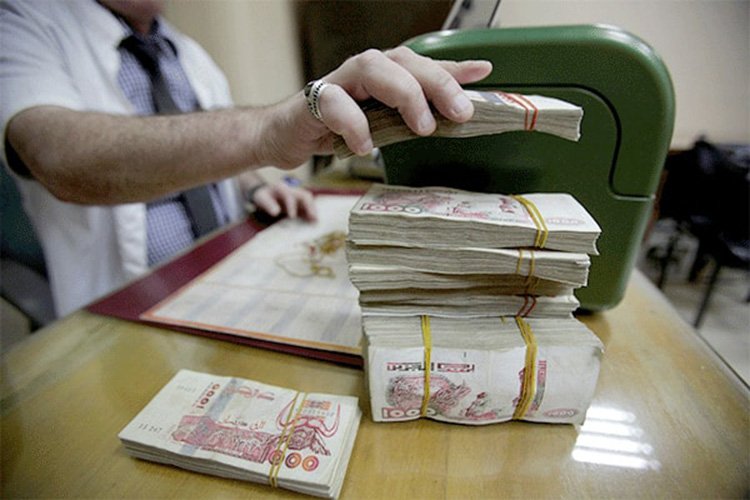
On the eve of social entry, banks have placed several files on the table in an attempt to attract the largest possible number of customers, taking advantage of the rising needs of families, professionals, and project owners, as the offers vary between consumer loans, financing projects, and renewing means of transportation, through savings products, all the way to bank cards and digital and international services, at a time when banking institutions are moving out of the framework of agencies and getting closer to the customer through exhibitions, open doors, and various events, that is, meeting with local groups.
Consumer loans are at the forefront of the files that returned to the forefront of banking activity during the month of September, given the rise in household expenses related to social income, as banks promote the possibility of financing the acquisition of a group of locally manufactured products, especially equipping and furnishing the home and electronic and electrical appliances, in accordance with the applicable legal and regulatory conditions.
In this context, the Algerian Popular Credit continues to provide clarifications to customers about the various aspects related to the consumer loan, including the possibility of prepayment of the loan, taking into account the commercial conditions applied by the bank or lending financial institution. It also clarifies the guarantees associated with this type of financing, which include insurance for inability to repay, in addition to insurance for death or absolute and final disability, allowing the remaining amounts to be covered in cases covered by the insurance contract.
On the other hand, the files presented to the banks are not limited to the needs of families, as financing of entrepreneurs and professionals has an important place in the offers of this period, in light of the banking institutions’ efforts to attract the category of project holders and small institutions searching for sources of financing to launch or expand their activities.
In this context, the National Bank of Algeria continues to promote financing solutions directed to project owners, including financing linked to the “Nesda” and “Ongam” devices, with an emphasis on accompanying project owners and helping them move from the idea stage to the completion stage, according to the conditions and procedures in force.
The file for renewing the public transportation facility for passengers has also entered the list of needs that banks are betting on financing, as the Algerian Popular Loan promotes financing the acquisition of new buses for the benefit of passenger transportation professionals. The program requires that the beneficiary be a professional in passenger transportation and possess a valid bond or exploitation decision, before obtaining a certificate of eligibility from the regionally competent transportation directorate, then submitting the financing application with the relevant agencies to complete the study of the file in cooperation with approved suppliers.
On the other hand, banks are opening another file related to attracting savings, as the National Savings and Reserve Fund promotes new savings products, including the “Progress” savings account, which combines savings and a number of banking services, and is based on a progressive return on savings, with secure savings, an interbank savings card, quarterly distribution of interest, and reserve insurance within an integrated package, in addition to free access to remote banking services “eBanking.”
Thus, banking competition is heading towards two parallel paths. On the one hand, there is the search for the customer who needs a loan to finance his needs or project, and on the other hand, there is the attraction of the customer who has savings and wants to deposit his money and benefit from the proceeds and accompanying banking services.
At the same time, work continues on the file of updating customer data and completing their banking information, within the framework of “Know Your Customer” procedures, known as “KYC”, where banks call on their customers to update the required information and documents and complete identification procedures, as part of the banking and regulatory requirements associated with dealing with accounts and banking services.
This file is of particular importance for customers who wish to benefit from various banking services, especially international cards and related services, as banks work to ensure the matching of customer data and the completion of their files, in parallel with expanding the scope of digital services and modern means of payment.
In the same context, the Foreign Bank of Algeria intensified its awareness campaigns related to the use of MasterCard cards abroad, providing customers with instructions on protecting the secret code and the correct behavior in the event of forgetting or losing it, while directing them to customer relations centers or banking agencies when needed.
Competition does not stop at the products offered, as banks have begun to intensify their presence outside agencies, by participating in economic and trade exhibitions, organizing open doors, and getting closer to citizens at the level of local communities, with the aim of providing information about loans, financing, savings products, cards, and electronic services, and answering customers’ inquiries directly.
This policy allows banks to closely identify the needs of citizens, professionals, and project owners, instead of waiting for them to go to agencies. It also gives them an opportunity to display several products in one space and attract new customers, at a time when simplifying procedures, speeding up file processing, updating customer data, and developing digital services and international cards have become part of a broader race to build a sustainable banking relationship with the customer.