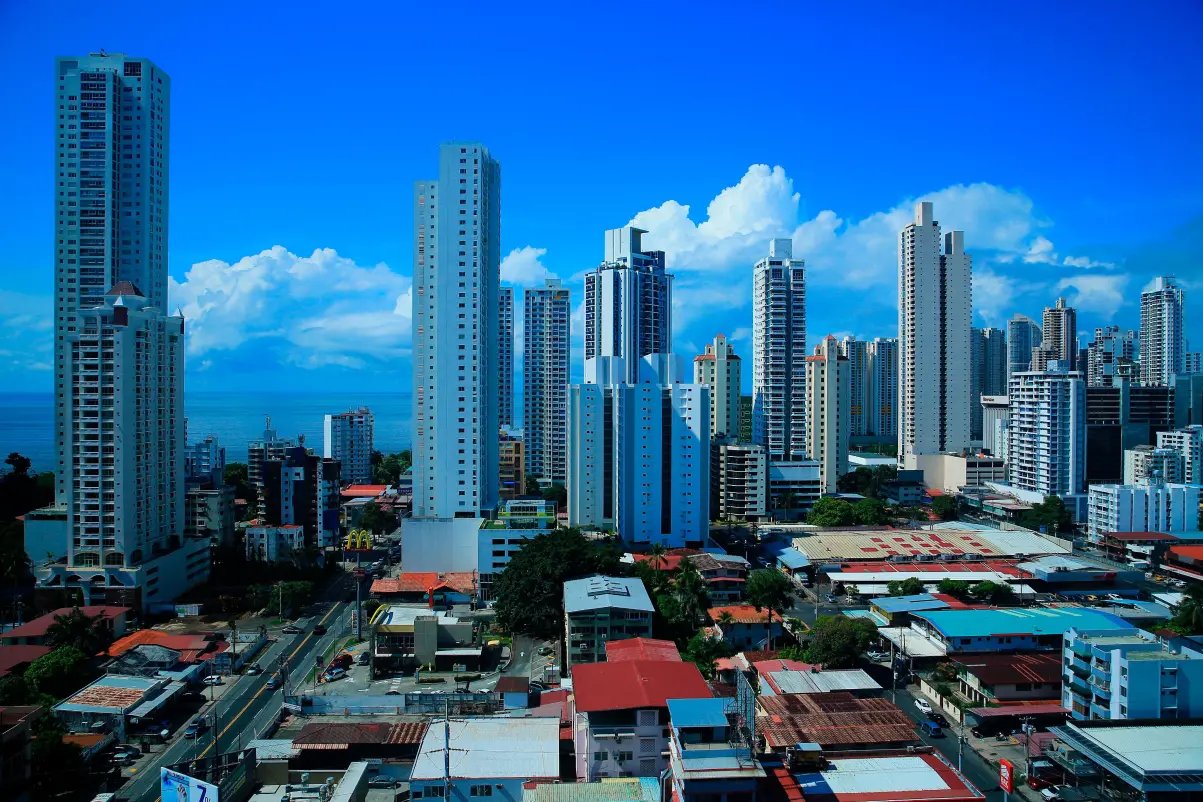
The creation of insurance to protect the savings of depositors of the International Banking Center that operates in Panama opens a new debate in the financial sector: how to guarantee the return of funds in the event of a possible banking crisis without transferring the cost of that protection to the savers themselves.
The initiative is being analyzed by the Superintendency of Banks of Panama (SBP), which is preparing a study to establish a deposit guarantee fund. Although the proposal has been evaluated for years, it gained relevance following the intervention of Ueno Bank of Paraguay, at the beginning of November.
This study will be carried out next year, which will evaluate the scope of coverage, the amounts protected, the administration model, the financing structure and its coordination with the bank resolution mechanisms.
Similarly, the SBP exclusively indicated to this newspaper that it will present a draft bank resolution law through the Ministry of Economy and Finance.
The main point of discussion is who will bear the cost of this mechanism. The SBP reported that the deposit guarantee fund would be financed by banking entities, although it acknowledged that it would have an impact on interest rates.
“It is very important that a technical evaluation be carried out on the subject that measures the pros and cons of a deposit guarantee fund,” commented Fernando Aramburú Porras, former Minister of Economy and Finance.
Among the aspects that must be evaluated is whether the example of Paraguay will be taken, which covers 75 minimum wages, or that of other countries with variable sums, explained Aramburú Porras.
“It is interesting that it is evaluated because when there is a run on a bank there is a lot of pressure from small savers to recover their funds because they live off of it,” said the former minister and businessman.
The impact that this mechanism could have on customers also raises concern among consumer organizations. Giovani A. Fletcher, from the Panamanian Institute of Consumer and User Law (Ipadecu), expressed his support for the evaluation, but warned about the risk of it translating into an increase in interest rates.
“We agree, but the fear that is put into perspective is that interest rates will rise in a market where they rise due to any circumstance,” Fletcher commented.
These insurances are applied in a good part of the countries in the Latin American region, Fletcher highlighted.
At the level of consumer associations in Latin America, the models that have been successful are those that have explicit coverage limited to small amounts. “A fund that is formed before any crisis with premiums paid by the banks and premiums that increase according to the risk for each bank.”
From the perspective of consumers, Pedro Acosta, representative of the National Union of Consumers and Users of the Republic of Panama (Uncurepa), considers that the review of the system can contribute to strengthening confidence in the banking center, based on the experiences that have occurred in the country.
Would it be expensive?
Former superintendent Olegario Barrelier (2006-2009) commented that during his administration an “in-depth” analysis was carried out with the technical staff of the SBP and the advice of the International Monetary Fund, the World Bank, the Bank of Spain and the United States Federal Reserve, which “led to the conclusion that, for the deposit base and affected depositors of the system at that time, the insurance was excessively expensive.”
For this reason, the responsibility of the banks in their credit management and the severity of the regulator were pointed out, since Panama does not have a Central Bank.
However, Barrelier contextualized that 17 years have passed and many things in the financial environment, technology and banking operations have changed.
“I think it is an excellent initiative for the SBP to review key aspects of the current process to improve it and maintain its leading continental competitive position.”
From the business sector, lawyer Rubén Castillo Gil and the Panamanian Association of Business Executives agree that the fundamental thing is to evaluate the cost for the savers themselves and analyze the technical aspects.
“Panama has a solid and well-regulated banking system. In any case, the debate is not unnecessary,” said Castillo Gil.
This would be an additional mechanism to strengthen confidence in the financial system and give greater protection to savers. However, support will depend on the terms and conditions, including who will bear the cost and how it will be financed.
“Its implementation could affect the competitiveness of our International Banking Center or translate into a decrease in the interest rates that depositors receive for their savings,” indicated the Panamanian Association of Business Executives (Apede).
The business organization, led by Alberto López Tom, highlighted the importance of any initiative in this direction being the product of extensive technical analysis and consultation with the various sectors to ensure the protection of savers and preserve the solidity, competitiveness and attractiveness of the banking center.