It extends until March 31, 2027 and includes a set of conditions for accreditation:
The Director General of Taxes is the entity authorized to grant the accreditation and its validity period is five years
Nationality, tax domicile are among the conditions, and subsidiaries for those wishing to distribute
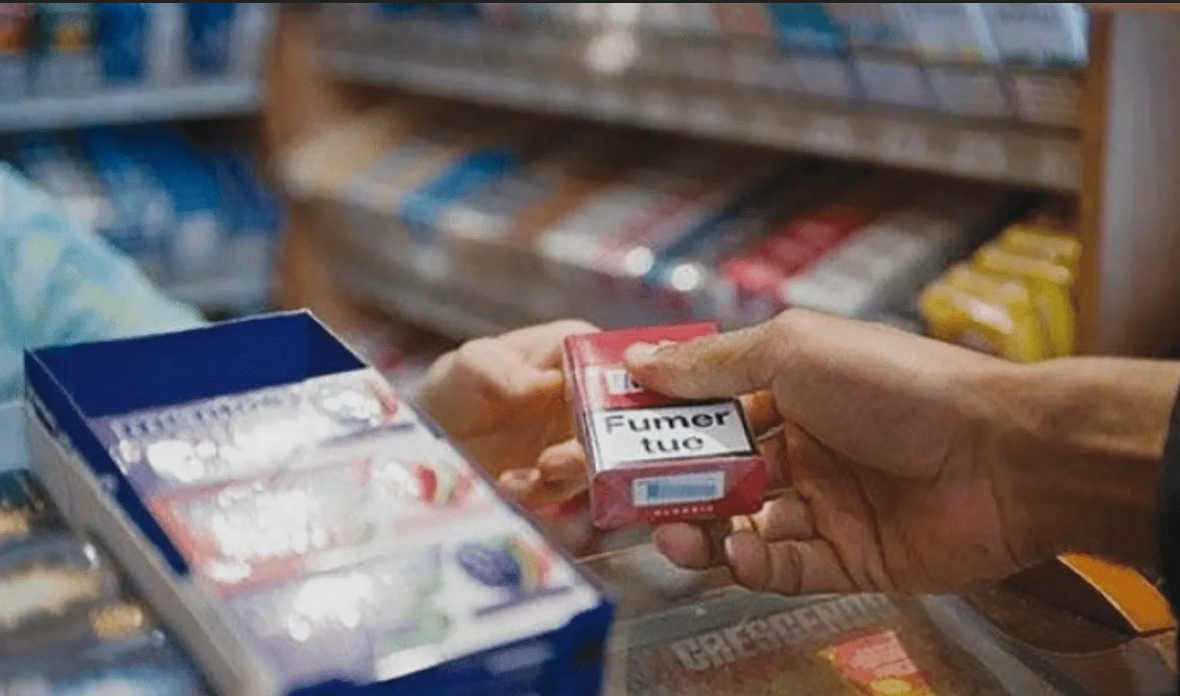
The Minister of Finance, Mohamed Lamine Labou, signed a new decision extending the deadlines for conforming the status of tobacco distributors with the new regulatory provisions until March 31, 2027, in accordance with the amendment of Article 12 of the decision dated June 24, 2025, which specifies the methods for granting accreditation to practice the activity of distributing tobacco materials, as well as the related book of conditions.
According to what was stated in Issue No. 75 of the Official Gazette dated October 25, 2026, the new decision, dated September 16, 2026, gives the concerned distributors of tobacco materials an additional period to regularize their situation and comply with the legal and regulatory conditions approved by the Ministry of Finance for practicing this activity. This amendment comes to extend the previously specified period, which required distributors to conform their status with the provisions of the new decision within one year from the date of its publication in the Official Gazette, as it became The deadline for compliance with these provisions is March 31, 2027.
On June 24, 2025, the Ministry of Finance issued a decision specifying the methods for granting accreditation to practice the activity of distributing tobacco materials, in addition to setting the book of conditions, the contents of which concerned dealers must adhere to. The decision stipulates that the practice of the activity of distributing tobacco materials is subject to obtaining an approval delivered by the Director General of Taxes, after submitting a file containing the required documents and subscribing to the book of conditions without reservation or restriction of its terms.
The text specifies the categories eligible to practice this activity, and it concerns natural persons of Algerian nationality who have a tax domicile in Algeria, in addition to companies subject to Algerian law, provided that their partners or shareholders are Algerian and have a tax domicile in Algeria. The decision also allows manufacturers of tobacco materials who hold accreditation as manufacturers to obtain accreditation to practice distribution activity as well, but in this case it is required to practice the distribution activity through a subsidiary company established for this purpose.
The decision stipulates that, in order to obtain a tobacco distributor accreditation, a file must be deposited with the Directorate of Large Enterprises or the Tax Directorate in the regionally competent state, as the case may be. The file includes the application for obtaining accreditation, a copy of the commercial registry, a copy of the tax identification certificate, as well as a copy of the biometric national identification card of the owner of the individual establishment or the manager of the company.
The file also includes a copy of the basic law of the commercial company, when necessary, and the document proving the appointment of its legal representative, as well as the title deed of the shop designated for the activity or its lease contract. The applicant must also submit a signed book of conditions, indicating his commitment to all the provisions and obligations stipulated therein without reservation.
Among the most prominent conditions included in the book of conditions is that tobacco distributors are obligated to provide a store with a total area of no less than 300 square meters, provided that there is an area of no less than 200 square meters at floor level in one continuous space. The store must include an area designated for the management of the institution or company, a distribution area, as well as a storage area.
It is also required that distribution shops be equipped with a permanent, illuminated and visible sign that allows immediate identification of the exploiter, and includes the name of the institution or its social designation and its address, with an explicit reference to the status of “distributor of tobacco materials.” The book of conditions also obliges distributors to declare to the competent tax authorities all the shops they exploit in distribution activity across the national territory, while ensuring that these shops comply with the applicable environmental, security and safety standards.
They must also submit a plan showing the storage locations for products intended for distribution, a list of the stores being used and the purpose assigned to each. As for activity control, the book of conditions stipulates the necessity of organizing tobacco storage stores in a way that ensures easy access to them on a permanent basis for tax officials.
Distributors are also required to take appropriate measures to secure doors and windows that directly overlook the public road or neighboring properties, in a way that prevents various forms of illegal removal or seizure of products. The distributor must ensure that tobacco sellers are supplied with various brands and types of tobacco materials, according to the quantities and prices specified in accordance with the applicable regulation, while adhering to the tax legislation regulating the storage, transportation and sale of these products.
The distributor is not allowed, according to the book of conditions, to sell his products except to tobacco sellers registered in this capacity in the commercial registry. He must also declare in advance to the competent tax administration any change that occurs in his status or in the data previously declared, according to the case. The June 2025 decision set the duration of accreditation at five years, subject to renewal, subjecting the practice of activity to the various conditions and obligations mentioned in the decision and the book of conditions. The text also included provisions related to the study of applications for accreditation, procedures for inspecting shops, and processing deadlines. Files, as well as cases of rejection of applications and ways to appeal them.
In the event that the accreditation application is rejected, the decision allows the person concerned to submit an appeal to the tax authorities within a period not exceeding 30 days from the date of his notification of the rejection decision, provided that the competent authorities decide on the appeal within a maximum period of 30 days from the date of its receipt. On the other hand, the accreditation can be withdrawn in the event of failure to respect one of the provisions of the book of conditions or violation of applicable legislation and regulations, after issuing a warning to the violator to settle his situation within eight days, in accordance with the procedures specified in Resolution. The accreditation is also withdrawn in the event of final cessation of activity.
The text requires the General Directorate of Taxes to send a quarterly status to the authority to control the tobacco and tobacco market, including the accreditations granted to distributors of tobacco materials and decisions to reject applications, on two paper and digital supports. By extending the period until March 31, 2027, the concerned distributors are required to take advantage of the additional period to conform their status to the new regulatory provisions, while adhering to the conditions of accreditation and the requirements of the book of conditions regulating the activity of distributing tobacco materials.